ESRS Topic Structure: What Changes with the Revised ESRS
Overview of the new ESRS topic structure in the revised ESRS (Delegated Regulation 2026/1563): changes, impact on companies, and relevance for the materiality assessment.
- The revised ESRS were adopted on 3 July 2026 and published in the EU Official Journal on 21 September 2026 as Delegated Regulation (EU) 2026/1563. They apply mandatorily from financial year 2027, cutting mandatory data points by over 60% and total data points by over 70%.
- The topic structure has been streamlined: under the draft, the three tiers (topics, sub-topics, sub-sub-topics) were reduced to two. The topic list in AR 16 is now only illustrative.
- Under the draft, E1 stays unchanged; E2 and E3 consolidate; E4 and E5 broaden scope; S1 and S2 merge; G1 integrates anti-corruption and animal welfare under corporate culture. Details of the final version may differ.
- Companies already using the ESRS should check whether removed sub-topics remain material for their specific sector and update their materiality assessment accordingly.
- The ESRS data points template helps companies track exactly which data points still apply after the restructuring.
The European Sustainability Reporting Standards (ESRS) form the core of the EU's Corporate Sustainability Reporting Directive (CSRD). Previously, the structure was three-tiered:
- Topics (e.g., climate change, biodiversity, workforce),
- Sub-topics,
- Sub-sub-topics (e.g., specific aspects like child labor, water withdrawal, or animal welfare).
This level of detail offered the advantage of clear guidance but brought high complexity for many companies, especially small and medium-sized enterprises (SMEs).
Changes to the ESRS Topic Structure: from Three to Two Tiers
The revision of the ESRS provided for a streamlining: instead of three tiers, there should only be topics and sub-topics; sub-sub-topics were to be removed or integrated into the higher level.
The revised ESRS were adopted on 3 July 2026 and published in the EU Official Journal on 21 September 2026 as Delegated Regulation (EU) 2026/1563. They apply mandatorily to financial years beginning on or after 1 January 2027; for financial year 2026 there is an option. Key points: mandatory data points cut by over 60%, total data points by over 70%, and a simplified materiality assessment (AR 16 only illustrative, top-down permitted, information filter).
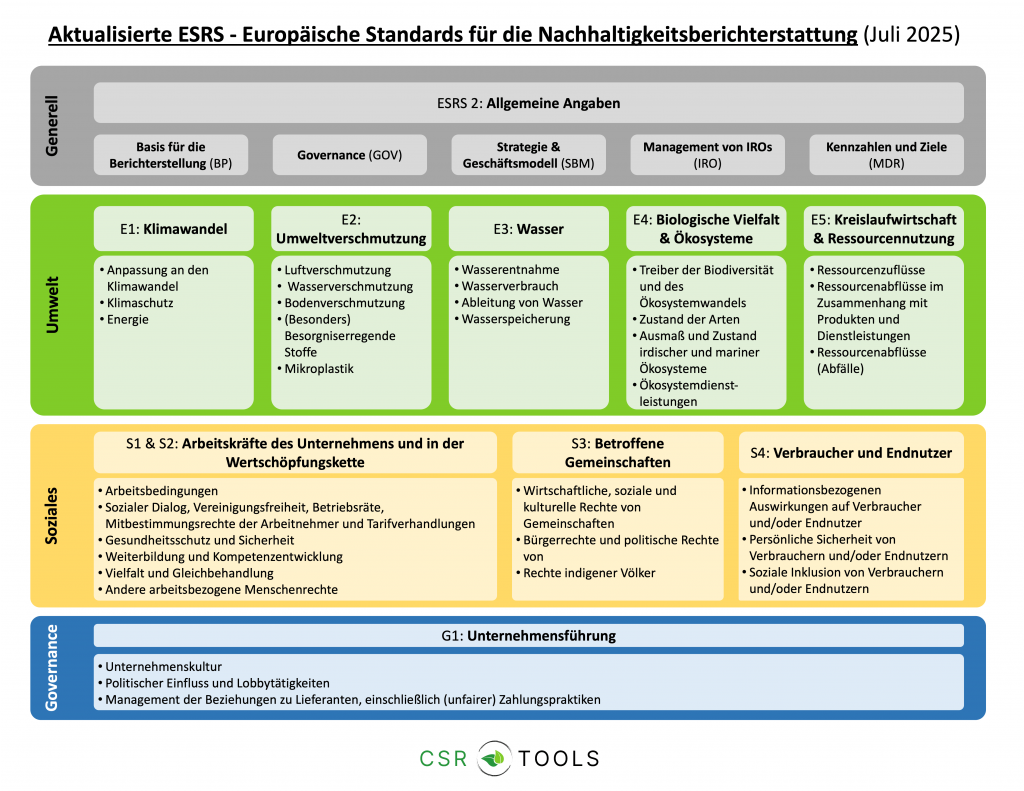
The following overviews reflect the EFRAG draft of the simplified ESRS. Details of the final version in Delegated Regulation (EU) 2026/1563 may differ. The text published in the EU Official Journal is authoritative.
Key Changes at a Glance (draft status):
- E1 Climate Change: No changes. Focus remains on climate protection, adaptation, and energy.
- E2 Pollution: "Pollution of living organisms and food resources" is removed (too sector-specific, hardly measurable). Substance-related topics are merged.
- E3 Water and Marine Resources: Sub-sub-topics like "water consumption" become independent sub-topics. "Discharge into oceans" is removed, "water storage" is newly added. The use of marine resources will be covered in other standards in the future.
- E4 Biodiversity and Ecosystems: Drivers such as invasive species are expanded. Examples (species extinction, land degradation) are removed for more flexibility and fewer checklists.
- E5 Circular Economy: Resource inflows and outflows remain, but services are now also considered. Marine resources are moved here.
- S1 and S2 Workforce: Own employees and value chain are merged into a unified logic for HR topics.
- S3 Affected Communities: Detailed topics (housing, nutrition, safety) are integrated into broader categories.
- S4 Consumers and End-users: Data protection, child protection, access to information, etc., merge into larger blocks.
- G1 Corporate Governance: Topics such as corruption, whistleblowing, and animal welfare are no longer reported individually, but within the framework of "corporate culture."
Why was the ESRS Topic Structure Changed?
The European Commission and EFRAG aim to achieve the following with the restructuring under the Omnibus package:
- Reduce complexity: The leaner topic structure reduces the effort for companies subject to reporting – since the Omnibus I package, from financial year 2027 only companies with more than 1,000 employees and more than €450 million net turnover.
- Create more flexibility: Companies should no longer tick off rigid checklists but identify relevant topics for their context. They can choose between a top-down and a bottom-up approach for identifying material topics.
- Strengthen the materiality assessment: Companies must prioritize for themselves, through the Materiality Assessment, which topics are material and thus subject to reporting.
Who is this Relevant for?
- SMEs and mid-sized companies that no longer fall under the CSRD obligation -- for them, the ESRS topic structure is mainly a point of orientation. Voluntary reporting is usually based on the VS (formerly VSME), which has its own, much leaner requirements.
- Large companies that must report comprehensively under the CSRD -- they benefit from a clearer structure but must carefully assess whether removed details remain material for their industry.
- CSRD consultancies, ESG software providers (such as Materiality Master) and auditors who need to adapt their tools and processes.
Since publication in the EU Official Journal on 21 September 2026, the revised ESRS are final; they enter into force on 10 November 2026 and apply mandatorily from financial year 2027. The overviews in this article are based on the draft – check the topic mapping for your reporting against the final text. As the topic list in AR 16 is now only illustrative, it serves as a starting point rather than a mandatory checklist, especially for the execution of the materiality assessment and internal data processes.
Note: The adjustment of the ESRS topic structure is one of numerous changes proposed in the ESRS Set 1 Exposure Draft.
The VSME has become the VS (Voluntary Standard): it was published on 21 September 2026 as Delegated Regulation (EU) 2026/1560 and has been in force since 24 September 2026. It is open to all companies not subject to CSRD reporting. From financial year 2027, a value-chain cap also applies: companies subject to the CSRD may not request information beyond the VS from value-chain partners with up to 1,000 employees.
Detailed Overview of all Changes in the ESRS Topic Structure
Note: The table reflects the draft status; details of the final version in Delegated Regulation (EU) 2026/1563 may differ.
| ESRS topic | Original sub-sub-topic | New mapping in 2025 draft | Status / change | Note / rationale |
|---|---|---|---|---|
| E1 Climate change | Climate change mitigation | Climate change mitigation | Unchanged | |
| E1 Climate change | Climate change adaptation | Climate change adaptation | Unchanged | |
| E1 Climate change | Energy | Energy | Unchanged | |
| E2 Pollution | Pollution of air | Pollution of air | Unchanged | |
| E2 Pollution | Pollution of water | Pollution of water | Unchanged | |
| E2 Pollution | Pollution of soil | Pollution of soil | Unchanged | |
| E2 Pollution | Pollution of living organisms and food resources | Removed | Removed | No disclosure / too sector-specific |
| E2 Pollution | Substances of concern | Substances of concern (incl. very high concern) | Merged | Merged with "very high concern" |
| E2 Pollution | Substances of very high concern | Substances of concern (incl. very high concern) | Merged | Merged into "concern" |
| E2 Pollution | Microplastics | Microplastics | Unchanged | |
| E3 Water and marine resources | Water consumption | Water consumption (now sub-topic) | Moved | From sub-sub to sub-topic |
| E3 Water and marine resources | Water withdrawals | Water withdrawals (now sub-topic) | Moved | From sub-sub to sub-topic |
| E3 Water and marine resources | Water discharges | Water discharges (now sub-topic) | Moved | From sub-sub to sub-topic |
| E3 Water and marine resources | Water discharges into oceans | Removed | Removed | Covered via ESRS 1 |
| E3 Water and marine resources | Water storage | Water storage | New | Newly introduced |
| E3 Water and marine resources | Extraction and use of marine resources | Moved to E5 | Moved | Now in E5 |
| E4 Biodiversity and ecosystems (direct drivers of biodiversity loss) | Climate change | Drivers of biodiversity and ecosystem change (terrestrial and marine) | Consolidated | Marine drivers added |
| E4 Biodiversity and ecosystems | Land-use change; freshwater/sea-use change | Drivers of biodiversity and ecosystem change | Consolidated | Broader scope |
| E4 Biodiversity and ecosystems | Direct exploitation | Drivers of biodiversity and ecosystem change | Consolidated | Broader scope |
| E4 Biodiversity and ecosystems | Invasive alien species | Drivers of biodiversity and ecosystem change | Consolidated | Broader scope |
| E4 Biodiversity and ecosystems | Pollution | Drivers of biodiversity and ecosystem change | Consolidated | Broader scope |
| E4 Biodiversity and ecosystems | Other | Drivers of biodiversity and ecosystem change | Consolidated | Broader scope |
| E4 Biodiversity and ecosystems (state of species -- examples) | Species population size (example) | Removed | Example removed | Examples deleted |
| E4 Biodiversity and ecosystems | Species extinction risk (example) | Removed | Example removed | Examples deleted |
| E4 Biodiversity and ecosystems | Land degradation (example) | Removed | Example removed | Examples deleted |
| E4 Biodiversity and ecosystems | Desertification (example) | Removed | Example removed | Examples deleted |
| E4 Biodiversity and ecosystems | Soil sealing (example) | Removed | Example removed | Examples deleted |
| E4 Biodiversity and ecosystems | Ecosystem services | Ecosystem services | Unchanged | Editorial |
| E5 Circular economy | Resource inflows incl. resource use | Resource inflows | Edited | "incl. use" removed |
| E5 Circular economy | Resource outflows: products and materials | Resource outflows: products and services | Expanded | Services added |
| E5 Circular economy | Waste | Waste | Unchanged | Editorial |
| E5 Circular economy | Marine resources (from E3) | Marine resources | Moved | Integrated here |
| S1 Own workforce | Secure employment | Merged into new combined S1/S2 block "Own workforce and workers in the value chain" | Merged | S1+S2 combined |
| S1 Own workforce | Working time | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Adequate wages | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Social dialogue | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Freedom of association; works councils; rights | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Collective bargaining (incl. coverage) | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Work-life balance | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Health and safety | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Gender equality and equal pay | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Training and skills development | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Employment and inclusion of persons with disabilities | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Measures against violence and harassment | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Diversity | Merged into S1/S2 block | Merged | |
| S1 Own workforce | Child labour | Merged into S1/S2 block (other labour-related rights) | Merged | |
| S1 Own workforce | Forced labour | Merged into S1/S2 block (other labour-related rights) | Merged | |
| S1 Own workforce | Adequate housing | Merged into S1/S2 block (other labour-related rights) | Merged | |
| S1 Own workforce | Privacy | Merged into S1/S2 block (other labour-related rights) | Merged | |
| S2 Workers in the value chain | (Analogous to S1: all sub-sub-topics) | Integrated into S1/S2 combined block | Merged | |
| S3 Affected communities | Adequate housing | Economic, social and cultural rights | Consolidated | |
| S3 Affected communities | Adequate food | Economic, social and cultural rights | Consolidated | |
| S3 Affected communities | Water and sanitation | Economic, social and cultural rights | Consolidated | |
| S3 Affected communities | Land-related impacts | Economic, social and cultural rights | Consolidated | |
| S3 Affected communities | Security-related impacts | Economic, social and cultural rights | Consolidated | |
| S3 Affected communities | Freedom of expression | Civil and political rights | Consolidated | |
| S3 Affected communities | Freedom of assembly | Civil and political rights | Consolidated | |
| S3 Affected communities | Impacts on human rights defenders | Civil and political rights | Consolidated | |
| S3 Affected communities | Free, prior and informed consent (FPIC) | Rights of indigenous peoples | Unchanged | |
| S3 Affected communities | Self-determination | Rights of indigenous peoples | Unchanged | |
| S3 Affected communities | Cultural rights | Rights of indigenous peoples | Unchanged | |
| S4 Consumers and end-users | Privacy | Information-related impacts | Consolidated | |
| S4 Consumers and end-users | Freedom of expression | Information-related impacts | Consolidated | |
| S4 Consumers and end-users | Access to information | Information-related impacts | Consolidated | |
| S4 Consumers and end-users | Health and safety | Personal safety | Consolidated | |
| S4 Consumers and end-users | Security of person | Personal safety | Consolidated | |
| S4 Consumers and end-users | Protection of children | Personal safety | Consolidated | |
| S4 Consumers and end-users | Non-discrimination | Social inclusion | Consolidated | |
| S4 Consumers and end-users | Access to products and services | Social inclusion | Consolidated | |
| S4 Consumers and end-users | Responsible marketing practices | Social inclusion | Consolidated | |
| G1 Business conduct | Corporate culture | Corporate culture (incl. anti-corruption, whistleblowers, animal welfare) | Consolidated | Integrated |
| G1 Business conduct | Corruption and bribery | Corporate culture | Consolidated | |
| G1 Business conduct | Whistleblowers protection | Corporate culture | Consolidated | |
| G1 Business conduct | Animal welfare | Corporate culture | Consolidated | |
| G1 Business conduct | Political influence and lobbying | Political influence and lobbying (editorial) | Unchanged | Minor edits |
| G1 Business conduct | Supplier relationships incl. payment practices | Supplier relationships (editorial) | Unchanged | Minor edits |
Conclusion on the Updated ESRS Structure
The ESRS streamlining brings both opportunities and challenges for companies:
- Opportunity: Less complexity and a clearer two-tier structure reduce reporting burden, especially for smaller teams.
- Opportunity: The simplified materiality assessment makes it easier to focus on what genuinely matters for your business.
- Challenge: Existing materiality assessments should be reviewed and adapted to the new ESRS topic structure.
- Challenge: Removed sub-topics (e.g., organisms, animal welfare as a standalone topic) may still be material for specific industries and should not be overlooked.
Companies should adapt their materiality assessment to the revised ESRS, check the topic mapping against the final text, and verify whether removed or merged sub-topics remain material in their sector. Resources like the CSRD Compass Newsletter help you stay up to date.
Keep track of which ESRS data points apply to your company after the restructuring. The ESRS data points template maps all relevant data points so you can immediately see what still applies and what has changed.
Frequently asked questions about the ESRS topic structure
What does the change from three tiers to two tiers mean in practice?
Under ESRS Set 1, companies had to navigate topics, sub-topics, and sub-sub-topics. According to the draft, the revision removes the sub-sub-topic level (details of the final version may differ). Those granular details are either merged into the sub-topic level above them or dropped entirely. The result is fewer line items to assess in your materiality process and fewer potential disclosure requirements.
Are the revised ESRS already in force?
They are final and enter into force on 10 November 2026. The revised ESRS were adopted on 3 July 2026 and published in the EU Official Journal on 21 September 2026 as Delegated Regulation (EU) 2026/1563. They apply mandatorily to financial years beginning on or after 1 January 2027. For financial year 2026, companies may choose between the previous ESRS (Set 1), Set 1 with reliefs, and the revised ESRS in full.
Do I need to redo my materiality assessment under the new structure?
You do not need to start from scratch, but a review is necessary. Some sub-sub-topics that were previously assessed separately are now merged or removed. You need to check that your existing assessments still cover the consolidated topics correctly, and confirm that any dropped topics are genuinely not material for your sector before removing them from your report.
Which ESRS standard changes the most under the restructuring?
According to the draft, the social standards see the most structural change. S1 (own workforce) and S2 (workers in the value chain) are merged into a single combined block. G1 also integrates previously standalone topics such as anti-corruption, whistleblower protection, and animal welfare under a single "corporate culture" sub-topic. E1 (climate change) is the only standard that remains entirely unchanged.