- The ESRS are the binding framework for sustainability reporting under the CSRD, developed by EFRAG and adopted by the European Commission.
- There are 12 standards covering general requirements, environmental, social, and governance topics. The originally planned sector-specific standards were scrapped with the Omnibus I package.
- The revised ESRS were adopted on 3 July 2026 and published in the EU Official Journal on 21 September 2026 as Delegated Regulation (EU) 2026/1563. They apply mandatorily to financial years beginning on or after 1 January 2027 – with more than 60% fewer mandatory data points.
- The LSME standard for listed SMEs has been dropped. Companies outside the CSRD scope can use the voluntary VS (formerly VSME), in force since 24 September 2026.
- You can download the first set of ESRS (2023) as a PDF from the European Commission website in 23 languages.
What are the European Sustainability Reporting Standards?
The European Sustainability Reporting Standards, or ESRS for short, mark a milestone in Europe's efforts to increase transparency and consistency in sustainability reporting (CSRD). Born out of pressure from public opinion, investor demands and the need to meet global climate targets, these standards provide a consistent basis for assessing and reporting companies' environmental, social and governance (ESG) performance. The standards were developed by EFRAG, the European Financial Reporting Advisory Group, as technical adviser to the European Commission and adopted by the Commission as delegated acts. EFRAG also advises the Commission on the endorsement of the International Financial Reporting Standards (IFRS) in the EU – but the IFRS themselves are set by the International Accounting Standards Board (IASB).
The main elements of the ESRS include:
- 12 ESRS guidelines: These relate to specific information that must be included in reports to provide a clear overview of a company's sustainability efforts.
- Comparability: The standards ensure that data is comparable across different companies and sectors.
- Clarity and consistency: With the ESRS, stakeholders can be sure that the information is recorded and presented according to a defined, consistent framework.
Is there only one ESRS standard?
In addition to the comprehensive ESRS for companies subject to the CSRD, which are the main focus of this article, EFRAG developed two further standards:
- ESRS LSME (ESRS for Listed Small- and Medium-Sized Enterprises): The LSME draft was intended to provide simplified reporting for listed SMEs. As listed SMEs are no longer subject to reporting under the Omnibus I package, this standard has been dropped.
- VS (formerly VSME): EFRAG published the VSME standard in December 2024 as a voluntary standard for non-listed SMEs. It has since evolved into the VS (Voluntary Standard).
The VS was adopted on 3 July 2026, published in the EU Official Journal on 21 September 2026 as Delegated Regulation (EU) 2026/1560 and has been in force since 24 September 2026. It builds on the VSME but is open to all companies that are not subject to CSRD reporting. In addition, a value-chain cap applies from financial year 2027: companies subject to the CSRD may not request information beyond the VS from value-chain partners with up to 1,000 employees.
A ready-to-use Word template for your VS sustainability report. Structured, practical, and adapted to the VS.
Why are the European Sustainability Reporting Standards important for Europe?
The importance of the ESRS goes far beyond mere reporting obligations. They are part of the Corporate Sustainability Reporting Directive (CSRD) and a key instrument that helps Europe consolidate its role as a pioneer in sustainability and responsible business conduct.
With the "European Green Deal", the European Union has an ambitious action plan to make Europe the first climate-neutral continent by 2050. To achieve this, European countries must reduce their net greenhouse gas emissions by at least 55% by 2030 compared to 1990 levels. In 2021, the energy industry (37%) and industry in Germany (20%) were responsible for over half of Germany's greenhouse gas emissions, so it is clear that companies must be held accountable to achieve these ambitious targets.
The EU Taxonomy and the ESRS provide companies with clear guidance on what information they should disclose and how it should be presented. This makes it easier for regulators to monitor progress towards the Green Deal targets and ensure that companies are doing their part.
The data provided by ESRS can also be used to assess the impact of the Green Deal on the European economy, identify potential barriers and take appropriate support measures.
In short, the Green Deal outlines the "what" and "why" for a more sustainable Europe. EFRAG's ESRS provide the "how" by delivering clear, consistent and comparable data on companies' sustainability efforts.
What is particularly relevant for companies with regard to ESRS?
How are the European Sustainability Reporting Standards structured?
There are two categories of ESRS:
- General standards
- Thematic standards (environmental, social and governance standards)
A third category – sector-specific standards – was originally planned but was scrapped with the Omnibus I package.
General standards
The general standards "ESRS 1 General Requirements" and "ESRS 2 General Disclosures" apply to sustainability aspects covered by the topic-specific standards.
They describe the general requirements for a sustainability report (such as structure and presentation) as well as the general disclosure obligations regarding the company's material sustainability aspects. Whether a topic is considered material for a company is determined by the principle of "double materiality". We have summarized the materiality assessment process in 4 steps in a separate article.
Step-by-step Excel template for your double materiality assessment, adapted to the revised ESRS. Automatically generates your materiality matrix.
Topic-related standards
The topic-related standards deal with specific sustainability topics and are divided into topics and sub-topics, and where applicable further sub-sub-topics. They may specify special requirements that go beyond and supplement "ESRS 2: General Disclosures". These specific requirements must also be followed by companies.
Sector-specific standards (scrapped)
Sector-specific standards were originally intended to apply industry-wide and address impacts, opportunities and risks not sufficiently covered by the topic-specific standards.
In January 2024, the introduction of sector-specific ESRS was postponed by 2 years until June 2026. Sector-specific standards were planned for the following industries: Oil and gas; Coal, quarrying and mining; Logistics and road transport; Agriculture, farming and fishing; Automotive and motor vehicles; Energy production and utilities; Food and beverages; Textiles, accessories, footwear and jewelry. With the Omnibus I package, the sector standards were scrapped. Sector-specific topics are instead covered through the materiality assessment and, where relevant, entity-specific disclosures.
What are the twelve ESRS standards?
| Standard | Name | Short description |
|---|---|---|
| ESRS 1 | General requirements | Sets out the structure of the ESRS, drafting requirements, underlying concepts and fundamental requirements for the preparation and presentation of sustainability-related information. |
| ESRS 2 | General information | Defines requirements for information a company must provide on all material sustainability aspects: governance, strategy, management of impacts, risks and opportunities, and key figures and targets. |
| ESRS E1 | Climate change | Covers a company's impact on climate change, efforts to limit global warming to 1.5°C, adaptation strategies, greenhouse gas emissions (Scope 1-3) and energy consumption. |
| ESRS E2 | Pollution | Covers actual and potential impacts on air, water and soil pollution, including substances of concern, actions to prevent and mitigate pollution, and the financial implications. |
| ESRS E3 | Water and marine resources | Requires disclosure of actual and potential impacts on water and marine resources, measures to mitigate negative impacts, sustainable water use strategies, and material risks and opportunities. |
| ESRS E4 | Biodiversity and ecosystems | Requires companies to report how they affect biodiversity and ecosystems (both positive and negative), including measures to mitigate impacts and restore biodiversity. |
| ESRS E5 | Circular economy | Covers resource efficiency, use of renewable resources and prevention of depletion of non-renewable resources, waste minimisation, and decoupling economic growth from material use. |
| ESRS S1 | Own workforce | Covers positive and negative influences on the company's own workforce: working conditions, equal treatment and opportunities, and other labour-related rights. |
| ESRS S2 | Workforce in the value chain | Defines disclosure requirements for a company's impact on workers in its value chain who are not part of the "own workforce". |
| ESRS S3 | Affected communities | Sets out how companies impact affected communities: economic, social and cultural rights; civil and political rights; specific rights of indigenous peoples. |
| ESRS S4 | Consumers and end users | Covers a company's impact on consumers and end users regarding information-related impacts, personal safety, and social inclusion. |
| ESRS G1 | Business conduct | Provides guidelines on corporate ethics and culture, management of supplier relationships (especially payment practices) and political influence and lobbying. |
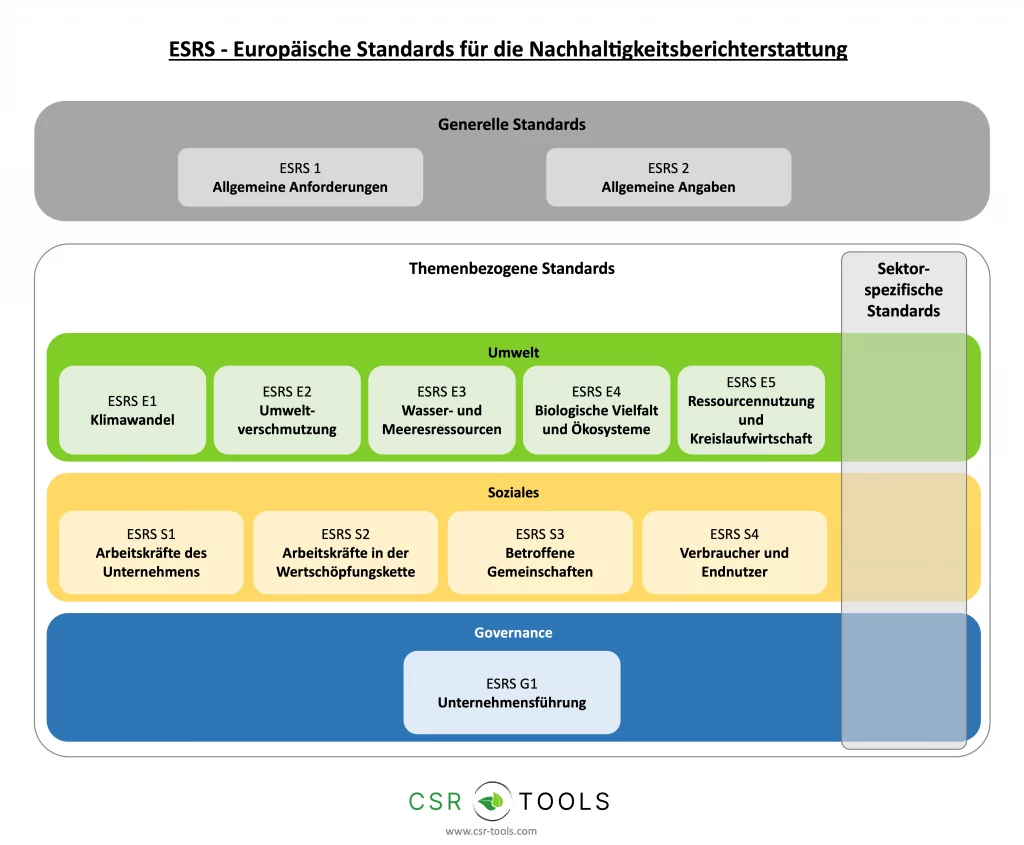
Note: The graphic still shows the originally planned level of sector standards, which was dropped with the Omnibus I package.
Can I download the European Sustainability Reporting Standards as a PDF?
Yes, the first set of European Sustainability Reporting Standards (ESRS) is available as a PDF download in 23 languages on the website of the European Commission. The version published on July 31, 2023 is available behind the "Annex C(2023)5303". We also provide a direct link to download the ESRS in German. Note that the document comprises 282 pages and is not particularly user-friendly.
Note: The linked PDF contains ESRS Set 1 from 2023. From financial year 2027, the revised ESRS (Delegated Regulation (EU) 2026/1563, published in the EU Official Journal on 21 September 2026) apply mandatorily. For the German language version of the revised ESRS, the DRSC has announced a corrigendum for October/November 2026 – until then, it is advisable to check the English version if in doubt.
For Set 1, EFRAG has published a list of all ESRS data points as an Excel file as well as further CSRD guidance to support companies in implementing the directive.
The complete list of ESRS data points as a structured Excel file. Helps you plan your reporting scope and track mandatory disclosures.
Are the ESRS standards final?
Yes. The Commission adopted the Delegated Act on the first set of ESRS on July 31, 2023. After receiving over 600 responses and comments, the standards were revised and simplified once more before publication. They set binding criteria for sustainability reporting in the EU for the first time.
As part of the Omnibus package, the ESRS have since been significantly streamlined – and the revised version is final too: The revised ESRS were adopted on 3 July 2026 and published in the EU Official Journal on 21 September 2026 as Delegated Regulation (EU) 2026/1563. They apply mandatorily to financial years beginning on or after 1 January 2027.
The EU Commission had published a draft of simplified ("revised") ESRS for consultation on 6 May 2026. The final version at a glance:
- Legal basis: Delegated Regulation (EU) 2026/1563, published in the EU Official Journal on 21 September 2026, in force from 10 November 2026
- Application: mandatory for financial years beginning on or after 1 January 2027; for financial year 2026, companies may choose between the previous ESRS, the previous ESRS with reliefs, or the revised ESRS in full (the choice must be disclosed)
- Mandatory data points cut by over 60%, total data points reduced by over 70%
- Simplified materiality assessment: AR 16 only illustrative, top-down approach permitted, information filter
Structure of the ESRS sustainability statement
ESRS requires companies to divide their sustainability statement into four parts:
- General information
- Environmental information
- Social information
- Governance information
As the information in the individual sections is not necessarily mutually exclusive, the company may refer to information already provided in another section to avoid duplication.
If the company provides material entity-specific information, it presents it together with the most relevant disclosures from the topical standards. The revised ESRS also give companies more flexibility in structuring and presenting their report.
Source: Appendix 1 "European Sustainability Reporting Standards (ESRS)"
When presenting sustainability data, it must be possible to distinguish between information required by the ESRS and other data contained in the management report. In addition, the format of the CSRD sustainability report must be accessible to both human readers and machine-readable systems.
There are numerous software solutions that can support the creation of a sustainability report. A PwC study presents the preferred tools.
European Sustainability Reporting Standards: Conclusion and outlook
The introduction of the ESRS marks a turning point in the way European companies report on their sustainability initiatives. These standards are a tool for transparency and responsibility, and can also serve as a catalyst for positive change in the business world. The ESRS are an elementary component of the CSRD and a relevant building block for achieving the goals of the Green Deal.
By following these guidelines, companies can improve their own sustainability efforts, build trust with stakeholders, increase their attractiveness to financial investors and strengthen their market position. Overall, the introduction of the ESRS demonstrates Europe's commitment to a more sustainable future and sets a benchmark for other regions around the world.
Frequently asked questions about ESRS
What is the difference between ESRS, CSRD, and EFRAG?
The CSRD is the EU directive that makes sustainability reporting mandatory for large companies. The ESRS are the technical standards that define exactly what must be reported. EFRAG (European Financial Reporting Advisory Group) develops the ESRS drafts as technical adviser to the European Commission, which adopts them as delegated acts.
Which companies must report under the ESRS?
The Omnibus directive has been in force since 18 March 2026: from financial year 2027, only companies with more than 1,000 employees AND more than €450m net turnover are subject to reporting (both criteria must be met). Companies that do not meet these thresholds are not required to report but may use the voluntary VS (formerly VSME), in force since 24 September 2026.
Will the ESRS change in 2026?
Yes. The revised ESRS were adopted on 3 July 2026 and published in the EU Official Journal on 21 September 2026 as Delegated Regulation (EU) 2026/1563. They apply mandatorily to financial years beginning on or after 1 January 2027; for financial year 2026 there is an option to apply them early. Mandatory data points are cut by over 60% and total data points by over 70%.
Where can I find practical help for ESRS implementation?
EFRAG provides the ESRS data points as an Excel file and further CSRD guidance. For your double materiality assessment, a step-by-step materiality analysis template can significantly speed up the process.